All Categories
Featured
Table of Contents
Notes: GDP development is specified as the yearly change in real (inflation-adjusted) GDP in the projection year compared to the previous year. Unemployment rate is as of December for each year. Core inflation is the year-over-year modification in the Consumer Prices Index, omitting unstable food, energy, alcohol, and tobacco rates, based on the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Economic Expert, KPMG in the UK, was joined by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Handling Partner, KPMG, to explore how homes and organizations might be affected and the obstacle for the brand-new federal government of delivering development while handling public finances.
The world economy grew by 3.3 per cent last year, nearly identical to the rates tape-recorded in 2023 and 2024. US development slowed from 2.8 per cent in 2024 to 2.2 per cent in 2025, as tariffs, tighter migration policy and raised uncertainty weighed on demand.
Structure Resistant and Ethical Supply Chains for International Reach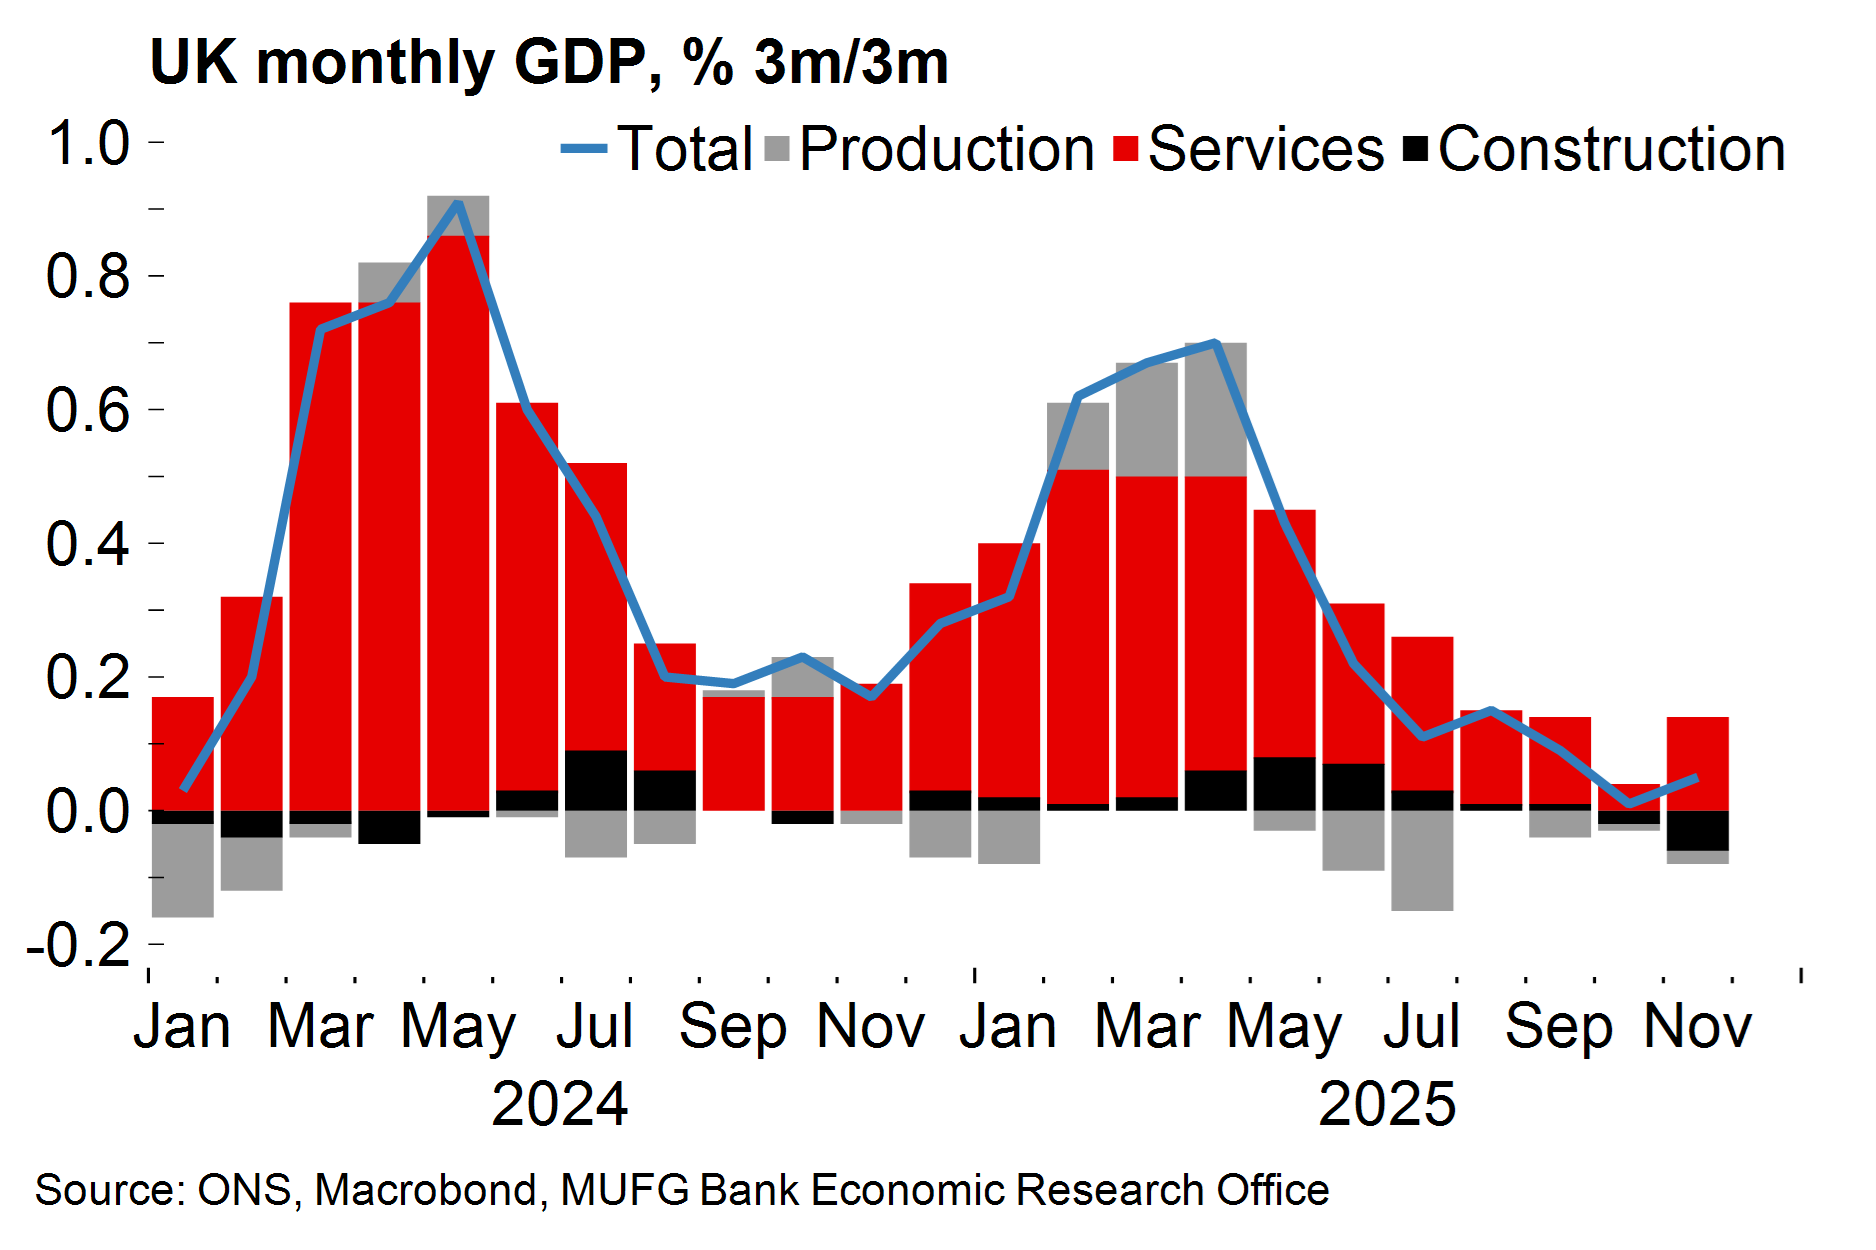
China and India kept quick expansion at 5.0 per cent and 7.4 percent respectively. This shows postponed tariff results and raised unpredictability dampening financial investment. Growth in sophisticated economies is set to slow to 1.8 percent in 2026 (United States 2.3 percent, Euro Location 1.3 per cent, Japan 0.8 per cent), with emerging markets growing by 4.0 percent (China 4.6 per cent, India 6.5 percent). US CPI inflation (2.7 percent in December 2025) is expected to average 2.6 per cent in 2026, reflecting tariff pass-through and a weaker dollar.
Why Sustainable Supply Chains Support British Industry Growth
The ECB has held its policy rate at 2 per cent and is likely to keep this position. Long-term bond yields stay elevated, with US 10-year Treasuries around 4.3 percent and Japanese 10-year government bond yields increasing dramatically to around 2.3 percent, up from 0.3 per cent in 2023. Tariff effects are still working through, while United States actions in Venezuela, tensions over Greenland, and China's export controls on crucial minerals raise the threats of additional disturbance.
GDP grew by 0.7 percent in Q1 as services brought forward activity ahead of the April increases in company National Insurance coverage Contributions and the National Living Wage. Growth then slowed to 0.2 percent in Q2 and 0.1 percent in Q3, kept back by Budget-related uncertainty and a cyber-attack affecting Jaguar Land Rover.
The near-term outlook is supported by residual fiscal growth and consistent consumption development. Beyond 2027, growth needs to settle somewhat above pattern at around 1.3-1.4 percent. Provided existing population projections, this implies per capita GDP growth remaining listed below 1 percent from 2027 onwards, highlighting the UK's persistent efficiency difficulty.
Adopting ESG Practices for Long-Term Success
Our main forecast is for CPI inflation to average 2.3 per cent in 2026 and to settle around target thereafter. Services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) remain annoyingly raised, pointing to consistent underlying price pressure.
Average incomes growth was 4.7 percent in the 3 months to November 2025. We project this to slow to around 3.6 per cent in 2026 and 3.1 per cent in 2027 as rising unemployment minimizes employees' bargaining power a small amounts vital for inflation to remain at target on a continual basis.
This shows sticking around unpredictability about the outlook and the scars from the recent inflation shock. We anticipate this elevated cost savings ratio to continue, constraining consumption development to around 1.0 percent in 2026 and 1.3 per cent in 2027. With inflation falling and unemployment rising, we expect 2 more 25 basis point cuts in 2026, bringing the rate to 3.25 per cent by year-endour estimate of the long-run neutral rate.
Evaluating UK Capital Investment Trends for 2026
On our forecast, the current budget plan is close to balance by 202930, suggesting no effective headroomBox C analyzes distinctions between the OBR's projection and ours. Public financial obligation continues to increase, with the debt-to-GDP ratio approaching 100 percent by decade-end, limiting the scope for discretionary fiscal assistance in future shocks.
Structure Resistant and Ethical Supply Chains for International ReachBy contrast, favorable net migration supports financial sustainability by expanding the working-age population and widening the tax base. Increases in company National Insurance coverage Contributions, substantial upratings of the National Living Wage (NLW), and reforms to work rights have raised the minimal expense of hiring by around 7 percent in real terms for an entry level position.

Latest Posts
Scaling the UK Talent Pool in 2026
Investment Banking Outlook for British Growth Entities
Sustainable Financing Vs. Legacy in the Mid-Market